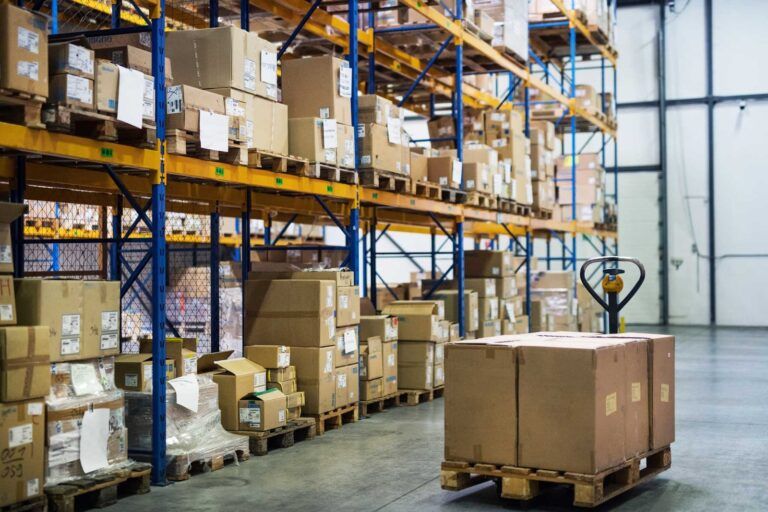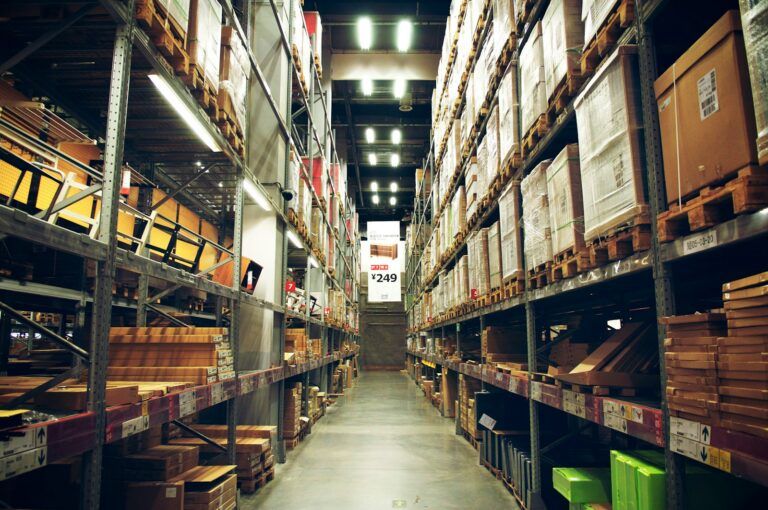

Stock counting, also called an inventory count or stocktake, means physically counting the products in your warehouse and comparing the result with the quantities in your system. Done well, it keeps you from overselling, tells you when to reorder and gives your accountant figures they can sign off. This guide explains the main types of stock counts, how to count stock in a warehouse step by step, how often to count, what to do when the numbers don’t match, and how to make every count faster and more accurate.
Quick answer: To do a stock count, freeze or record stock movements, count each location with a barcode scanner or count sheet, recount any differences, then adjust your system and investigate the cause. Most growing eCommerce brands combine a yearly full count (often required for the annual accounts) with regular cycle counts, counting their fastest-selling and most valuable products most often.
Jump to: What is stock counting · Types of stock counts · How to count stock · How often to count · Discrepancies · Inventory accuracy · Best practices · Common problems · FAQ
What is stock counting?
A stock count is the physical check of how many units of each product (SKU) you hold, and where. The counted quantity is compared with the quantity in your inventory system or warehouse management system (WMS). Any difference is a discrepancy that needs to be explained and corrected.
You will see several terms used for the same idea:
- Stock count / inventory count: counting some or all of your stock.
- Stocktake / physical inventory: usually a full count of all stock, often at year end.
- Cycle count: counting a small part of your stock on a rolling schedule.
Why stock counting matters
- No overselling. If your system shows 50 units but the shelf holds 42, your shop will sell 8 products you do not have. That means cancelled orders, unhappy customers and bad reviews.
- Better reordering. Accurate stock levels let you reorder the right quantity at the right time, avoiding both stockouts and cash tied up in excess stock.
- Finding losses early. Regular counts show damage, theft, mispicks and receiving mistakes while they are still easy to trace.
- Correct accounts. Stock is an asset on your balance sheet. In many countries businesses must count it at least once a year (see how often to count).
Types of stock counts
There are five common types of stock taking. Most businesses use two or three of them together.
| Type | What you count | Best for | Downside |
|---|---|---|---|
| Full (periodic) count | Everything, at one time | Year-end accounts, small ranges | Operations often stop during the count |
| Cycle count | A few locations or SKUs each day or week | Busy warehouses that cannot stop | Needs a schedule and discipline |
| ABC count | Cycle counts weighted by value or sales | Large ranges with a few key products | Requires sales and value data |
| Spot check | One SKU or location, unplanned | Checking a suspected problem | Not a complete picture |
| Perpetual inventory | System updated with every movement, verified by cycle counts | Any operation with a WMS and scanners | Only as good as the scanning discipline |
Full periodic count
A full count, sometimes called a wall-to-wall count, checks every unit in the warehouse at the same time. It is thorough, but it usually means pausing receiving and shipping for a day or more, so most businesses do it once a year, at year end.
Cycle counting
With cycle counting you count a small part of your stock on a rolling schedule, for example one aisle a day or 5% of your SKUs a week. Over a quarter or a year, every location is counted, and the warehouse keeps running. Problems are found within weeks instead of at year end.
ABC counting
ABC counting is cycle counting with priorities. You split your SKUs into three groups and count the most important ones most often:
| Group | Typical share | Common starting frequency |
|---|---|---|
| A: highest value or fastest sellers | About 20% of SKUs, most of the value | Monthly |
| B: middle group | About 30% of SKUs | Quarterly |
| C: low value, slow movers | About 50% of SKUs, little of the value | Twice a year |
These frequencies are a starting point. Count more often if a group keeps showing discrepancies.
Spot checks and blind counts
A spot check is an unplanned count of one product or location, for example after a customer reports a missing item. In a blind count, counters do not see the expected quantity, so they cannot simply confirm what the system says. Blind counts are slower but give more reliable results.
Perpetual inventory
In a perpetual system, every receipt, pick, return and transfer is scanned, so the stock level updates in real time. Cycle counts then check that the records stay right. This is how modern warehouses work, and it is what lets you sell from live stock on several channels at once.
How to count stock in a warehouse, step by step
- Plan the count. Decide what you count (all stock, an aisle, A items), when, and who. Avoid peak days and month-end order surges.
- Prepare the warehouse. Put away all received goods, return stray items to their locations and make sure every location and product label is readable.
- Freeze or record movements. For a full count, pause receiving and picking. For a cycle count, block only the locations being counted, or record any movements during the count.
- Count by location. Work location by location, scanning the location barcode and then each product. Use count sheets only as a backup. Count opened cartons and loose units separately.
- Compare with the system. The WMS or inventory software lists every difference between counted and expected quantities.
- Recount differences. A second person recounts every location with a discrepancy before anything is changed.
- Adjust and record. Update the system with the confirmed quantity, and record the reason for each adjustment.
- Investigate and fix the cause. Look for the process that created the difference, such as receiving errors, mispicks or unrecorded returns, and fix it so it does not happen again.
How often should you count stock?
It depends on your volume, the value of your stock and how often you find problems. A common setup for eCommerce brands:
- Once a year: a full count, or a documented cycle counting programme, for the annual accounts.
- Every week: cycle counts of a few locations, prioritising A items.
- After events: spot checks after a large inbound delivery, a peak season, a system change or a customer complaint.
Annual counts are often a legal requirement. In Germany, for example, businesses must take an inventory at the end of each financial year under §240 of the Commercial Code (HGB), and §241 HGB allows a permanent (perpetual) inventory or a count close to the balance sheet date instead of a single count on that day. In the UK, company accounting records must include statements of stock held at year end under section 386 of the Companies Act 2006. Check the rules in your country with your accountant.
What to do when the count doesn’t match
Discrepancies are normal. What matters is how you handle them. Take a simple example: you count 100 units, the WMS shows 96, and a recount finds 99.
- The first count was wrong by one unit, which shows why every difference needs a recount before you adjust.
- The confirmed quantity is 99, three more than the system expected. Extra stock usually means a missed receipt, a return that was put away but not booked, or a pick recorded but not actually taken from that location.
- Check recent movements for the SKU and the neighbouring locations before adjusting. A plus at one location is often a minus at another.
Set a tolerance, for example any difference above 2% or above a certain value, that always triggers an investigation. Small, random differences on cheap items can be adjusted with a reason code.
How to measure inventory accuracy
The most common measure is inventory record accuracy (IRA): the share of counted locations or SKUs where the system quantity matches the counted quantity, within your tolerance.
Inventory accuracy (%) = locations counted with no discrepancy ÷ total locations counted × 100. For example, 485 correct locations out of 500 counted = 97% accuracy.
Track the figure every month. A falling score is an early warning that a process, such as receiving or returns, needs attention.
Best practices for accurate stock counts
Organise your storage
- Give every product a fixed or system-assigned location, and label every location with a barcode.
- Keep one SKU per location where possible. Mixed locations are the most common source of counting errors.
- Keep aisles clear and avoid stacking products where they hide other stock.
Use barcode scanning
Scanning the location and each product removes most manual errors: no misread numbers, no wrong SKUs, no lost count sheets. RFID can speed up counts further for high volumes of tagged goods such as apparel, but barcodes are enough for most brands.
Use a WMS as your single source of truth
A WMS records every movement and lets you schedule cycle counts, run blind counts and approve adjustments. Waredock WMS shows live stock per SKU, location and warehouse, supports regular cycle counts and uses product images and scan checks to prevent mispicks that later turn into count differences.
Train and rotate counters
Give counters clear instructions, especially for cartons, inner packs and damaged goods, and let a different person do recounts.
Common stock counting problems and how to fix them
Human error and miscounts
Skipped locations, wrong numbers and confusion between units and cartons are the classic mistakes. Fix: scan instead of writing, use blind counts and always recount differences.
Peak season surges
When stock moves fast, records drift and there is no time to count. Fix: count your A items just before peak, avoid full counts during it and run a set of cycle counts straight afterwards.
Limited staff and time
A full count can take your whole team away from orders. Fix: switch to cycle counting so a few minutes of counting each day replaces one disruptive annual shutdown, where your accounting rules allow it.
Receiving and returns errors
Many discrepancies start at the door: deliveries booked with the wrong quantity, or returns put back on the shelf without being recorded. Fix: count and scan every inbound delivery against the advance shipping notice, and process returns through the system before restocking.
If you outsource fulfilment, ask your 3PL how often they cycle count, what accuracy they achieve and how they report adjustments. Read more about eCommerce fulfilment and warehouse storage with Waredock.
Frequently asked questions
What is a stock count?
A stock count is the physical counting of the products you hold, compared with the quantities in your inventory system. It can cover all stock (a full count or stocktake) or a small part of it (a cycle count).
What are the types of stock taking?
The main types are the full periodic count, cycle counting, ABC counting, spot checks and perpetual inventory. Many businesses combine a yearly full count with regular cycle counts of their most important products.
How do you count stock in a warehouse?
Plan the count, put away all stock, freeze or record movements, count location by location with a barcode scanner, compare with the system, recount any differences, adjust the records and investigate the cause.
How often should you do a stock count?
Most businesses do at least one full count or documented count programme a year for their accounts, plus weekly cycle counts. Count your highest-value and fastest-selling products most often, for example monthly.
What is the difference between a stock count and cycle counting?
A stock count can mean any count, but often refers to a full count of everything at once. Cycle counting counts a small part of the stock on a rolling schedule, so the warehouse keeps running and errors are found sooner.
What is a good inventory accuracy rate?
Well-run warehouses aim for inventory record accuracy in the high 90s per cent. Track your own figure monthly and investigate when it falls.
Sources
- German Commercial Code (HGB), §240 Inventar and §241 Inventurvereinfachungsverfahren
- UK Companies Act 2006, section 386: duty to keep accounting records